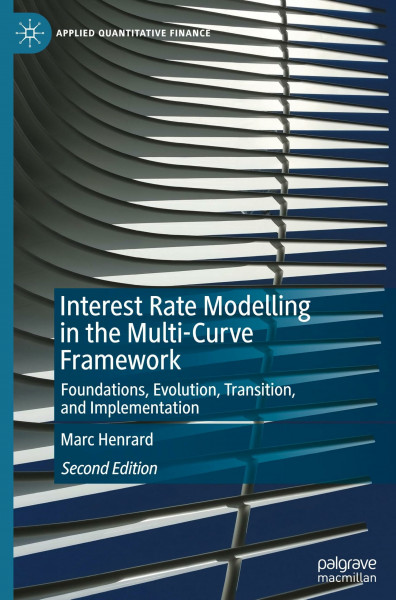
Interest Rate Modelling in the Multi-Curve Framework: Foundations, Evolution, Transition, and Implementation (Applied Quantitative Finance)
Kurzinformation
 Handgeprüfte Gebrauchtware
 Schnelle Lieferung
 Faire Preise
inkl. MwSt. Versandinformationen
Lieferzeit 1-3 Werktage
Lieferzeit 1-3 Werktage

Beschreibung
A new standard in interest rate modelling, called the multi-curve framework, emerged after the financial crisis. The framework covers two important market features: the collateralisation of derivative trades and the spread between different rate benchmarks. This book starts from the collateral mechanisms and builds the full framework from the foundations through all the technical and financial details. It kicks off with the collateral discounting in all its variants: domestic cash, foreign cash, or other assets and then introduces the different benchmarks and their associated spreads. Following the discontinuation of certain benchmarks, part of the book is dedicated to the transition and the emergence of the overnight benchmark dominance in certain currencies. Based on the theoretical framework of the first chapters, the important curve calibration mechanism is analysed in detail. Many instruments are investigated with all their practical peculiarities. Most of the book is dedicated to the understanding of the “static” interest rate curves. The book’s last part deals with the building blocks of any dynamic model explaining their future behaviour and apply some of those models to the most liquid instruments. Based on more than 25 years of experience as a trader and quantitative analyst in the related markets, the author includes many details on implementation in libraries and using the framework in risk management, which will be of interest to traders, risk managers, quantitative analysts, and actuaries alongside professors, researchers, and students of banking, insurance, risk management, and quantitative finance.
Produktdetails
So garantieren wir Dir zu jeder Zeit Premiumqualität.
Entdecke mehr vom Verlag