LeafNachhaltiges Unternehmen CoinFaire Preise PackageSchneller und kostenloser Versand ab 14,90 € Bestellwert
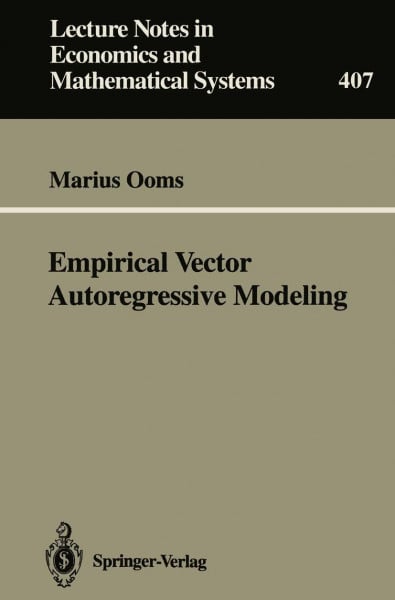
Empirical Vector Autoregressive Modeling (Lecture Notes in Economics and Mathematical Systems) (Lecture Notes in Economics and Mathematical Systems, 407, Band 407)

Empirical Vector Autoregressive Modeling (Lecture Notes in Economics and Mathematical Systems) (Lecture Notes in Economics and Mathematical Systems, 407, Band 407)

inkl. MwSt. Versandinformationen

Lieferzeit 1-3 Werktage

104,03 €

Lieferzeit 1-3 Werktage

Kurzinformation
Sprache:
Englisch
ISBN:
9783540577072
Verlag:
Seitenzahl:
404
Auflage:
-
Erschienen:
1994-04-28
Mit diesem Kauf sparst Du 2,06 kg CO2

Mehr Informationen zum Zustand
Green Tree

Gebrauchte Bücher kaufen

Information
Das Buch befindet sich in einem sehr guten, unbenutzten Zustand.
Information
Das Buch befindet sich in einem sehr guten, gelesenen Zustand. Die Seiten und der Einband sind intakt. Buchrücken/Ecken/Kanten können leichte Gebrauchsspuren aufweisen.
Information
Das Buch befindet sich in einem guten, gelesenen Zustand. Die Seiten und der Einband sind intakt. Buchrücken/Ecken/Kanten können Knicke/Gebrauchsspuren aufweisen.
  • Starke Gebrauchsspuren, Seiten und Bindung beschädigt
  • Knicke oder Markierungen nicht mehr als 20%
  • CDs und Zugangscodes können fehlen
  • Auflage kann abweichen
Information
Das Buch befindet sich in einem lesbaren Zustand. Die Seiten und der Einband sind intakt, jedoch weisen Buchrücken/Ecken/Kanten starke Knicke/Gebrauchsspuren auf. Zusatzmaterialien können fehlen.

Neues Buch oder eBook (pdf) kaufen

Information
Neuware - verlagsfrische aktuelle Buchausgabe.
Natural Handgeprüfte Gebrauchtware
Coins Schnelle Lieferung
Check Faire Preise

inkl. MwSt. Versandinformationen

Lieferzeit 1-3 Werktage

104,03 €

Lieferzeit 1-3 Werktage

Weitere Zahlungsmöglichkeiten  
Zahlungsarten

Beschreibung

Empirical Vector Autoregressive Modeling (Lecture Notes in Economics and Mathematical Systems) (Lecture Notes in Economics and Mathematical Systems, 407, Band 407)

The main subject of this book is empirical application of multivariate linear time series model on quarterly or month- ly economic data to discoverand describe important dynamic relationships between the variables of interest. The book stresses "real-life" application and the selection of data analytic tools. Simple numerical examples and some more al- gebraicexercises are used to illustrate major points. Rele- vant old and recent results from over 400 authors and refe- rences from econometrics, mathematical statistics, time se- ries analysis, economics and descriptve statistics are dis- cussed. Appropriate use of multivariate time series models requires an intimate knowledge of relevant characteristics of thedata.One can obtain this using a method that combines influence analysis (which data points contain the major part of the information? ) and diagnostic checking (does the model describe the interesting part of the information well enough? ). For economic time series these issuses are (the type of) nonstationarity of the trend and seasonal compo- nent, be it of the (fractional) "unit root" type or of the changing parameter type (structural breaks), both in a unva- riate and a multivariate context. The book introduces new graphical and statistical methodes to improve the understan- ding of seasonality, outliers, structural breaks, pushing trends and pulling equilibria in aparticular data set.

Produktdetails
Einband:
paperback
Seitenzahl:
404
Erschienen:
1994-04-28
Sprache:
Englisch
EAN:
9783540577072
ISBN:
9783540577072
Verlag:
Gewicht:
712 g
Auflage:
-
Alle gebrauchten Bücher werden von uns handgeprüft.
So garantieren wir Dir zu jeder Zeit Premiumqualität.

Über den Autor


Entdecke mehr vom Verlag


Akzeptabel
104,03 €
Entdecke mehr zum Thema