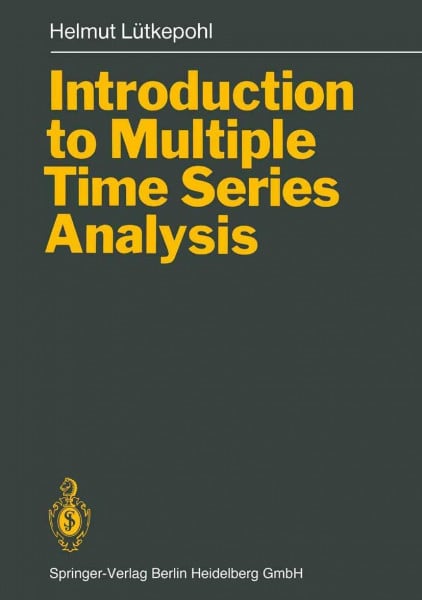
Introduction to Multiple Time Series Analysis
Kurzinformation
 Handgeprüfte Gebrauchtware
 Schnelle Lieferung
 Faire Preise
inkl. MwSt. Versandinformationen
Lieferzeit 1-3 Werktage
Lieferzeit 1-3 Werktage

Beschreibung
This graduate-level textbook deals with analyzing and forecasting multiple time series. It considers a wide range of multiple time series models and methods. The models include vector autoregressive, vector autoregressive moving average, cointegrated and periodic processes as well as state space and dynamic simultaneous equations models. Least squares, maximum likelihood and Bayesian methods are considered for estimating these models. Different procedures for model selection or specification are treated and a range of tests and criteria for evaluating the adequacy of a chosen model are introduced. The choice of point and interval forecasts as well as innovation accounting are presented as tools for structural analysis within the multiple time series context.
Produktdetails
So garantieren wir Dir zu jeder Zeit Premiumqualität.
Entdecke mehr vom Verlag