


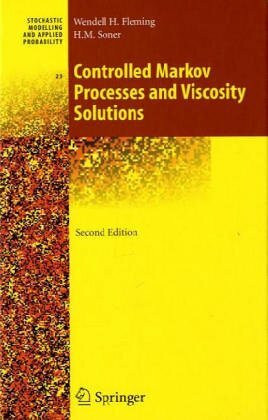
Controlled Markov Processes and Viscosity Solutions (Stochastic Modelling and Applied Probability)
Kurzinformation
 Handgeprüfte Gebrauchtware
 Schnelle Lieferung
 Faire Preise
inkl. MwSt. Versandinformationen
Lieferzeit 1-3 Werktage
Lieferzeit 1-3 Werktage

Beschreibung
This book is intended as an introduction to optimal stochastic control for continuous time Markov processes and to the theory of viscosity solutions. The authors approach stochastic control problems by the method of dynamic programming. The text provides an introduction to dynamic programming for deterministic optimal control problems, as well as to the corresponding theory of viscosity solutions. Also covered are controlled Markov diffusions and viscosity solutions of Hamilton-Jacobi-Bellman equations. The authors have tried, through illustrative examples and selective material, to connect stochastic control theory with other mathematical areas (e.g. large deviations theory) and with applications to engineering, physics, management, and finance.
Produktdetails
So garantieren wir Dir zu jeder Zeit Premiumqualität.


