LeafNachhaltiges Unternehmen CoinFaire Preise PackageSchneller und kostenloser Versand ab 14,90 € Bestellwert
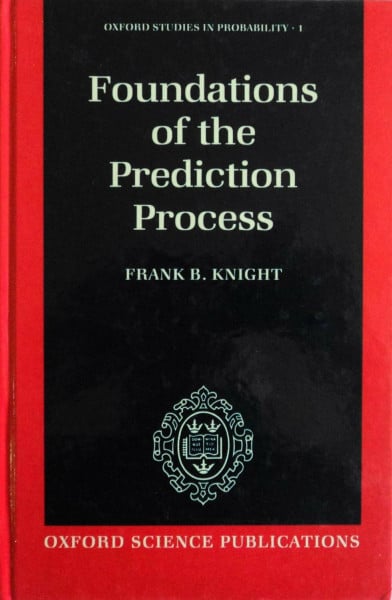
Foundations of the Prediction Process (Oxford Studies in Probability)

Foundations of the Prediction Process (Oxford Studies in Probability)

inkl. MwSt. Versandinformationen

Lieferzeit 1-3 Werktage

147,98 €

Lieferzeit 1-3 Werktage

Kurzinformation
Sprache:
Englisch
ISBN:
9780198535935
Seitenzahl:
260
Auflage:
-
Erschienen:
1992-02-01
Mit diesem Kauf sparst Du 2,06 kg CO2

Mehr Informationen zum Zustand
Green Tree

Gebrauchte Bücher kaufen

Information
Das Buch befindet sich in einem sehr guten, unbenutzten Zustand.
Information
Das Buch befindet sich in einem sehr guten, gelesenen Zustand. Die Seiten und der Einband sind intakt. Buchrücken/Ecken/Kanten können leichte Gebrauchsspuren aufweisen.
  • Sauberer Zustand, Seiten und Bindung etwas abgenutzt
  • Knicke oder Markierungen nicht mehr als 5%
  • CDs und Zugangscodes verwendbar
Information
Das Buch befindet sich in einem guten, gelesenen Zustand. Die Seiten und der Einband sind intakt. Buchrücken/Ecken/Kanten können Knicke/Gebrauchsspuren aufweisen.
Information
Das Buch befindet sich in einem lesbaren Zustand. Die Seiten und der Einband sind intakt, jedoch weisen Buchrücken/Ecken/Kanten starke Knicke/Gebrauchsspuren auf. Zusatzmaterialien können fehlen.

Neues Buch oder eBook (pdf) kaufen

Information
Neuware - verlagsfrische aktuelle Buchausgabe.
Natural Handgeprüfte Gebrauchtware
Coins Schnelle Lieferung
Check Faire Preise

inkl. MwSt. Versandinformationen

Lieferzeit 1-3 Werktage

147,98 €

Lieferzeit 1-3 Werktage

Weitere Zahlungsmöglichkeiten  
Zahlungsarten

Beschreibung

Foundations of the Prediction Process (Oxford Studies in Probability)

This book presents a unified treatment of the prediction process approach to continuous time stochastic processes. The underling idea is that there are two kinds of time: stationary physical time and the moving observer's time. By developing this theme, the author develops a theory of stochastic processes whereby two processes are considered which coexist on the same probability space. In this way, the observer' process is strongly Markovian. Consequently, any measurable stochastic process of a real parameter may be regarded as a homogeneous strong Markov process in an appropriate setting. This leads to a unifying principle for the representation of general processes in terms of martingales which facilitates the prediction of their properties. While the ideas are advanced, the methods are reasonable elementary and should be accessible to readers with basic knowledge of measure theory, functional analysis, stochastic integration, and probability on the level of the convergence theorem for positive super-martingales.

Produktdetails

Einband:
hardcover
Seitenzahl:
260
Erschienen:
1992-02-01
Sprache:
Englisch
EAN:
9780198535935
ISBN:
9780198535935
Gewicht:
567 g
Auflage:
-
Alle gebrauchten Bücher werden von uns handgeprüft.
So garantieren wir Dir zu jeder Zeit Premiumqualität.

Über den Autor


Entdecke mehr vom Verlag


Gut
147,98 €
Entdecke mehr zum Thema