LeafNachhaltiges Unternehmen CoinFaire Preise PackageSchneller und kostenloser Versand ab 14,90 € Bestellwert
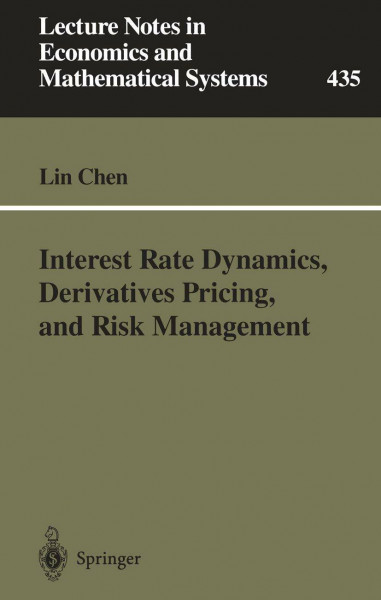
Interest Rate Dynamics, Derivatives Pricing, and Risk Management (Lecture Notes in Economics and Mathematical Systems, 435, Band 435)

Interest Rate Dynamics, Derivatives Pricing, and Risk Management (Lecture Notes in Economics and Mathematical Systems, 435, Band 435)

Du sparst 52,84 € (49%)

inkl. MwSt. Versandinformationen

Lieferzeit 1-3 Werktage

54,16 €

Lieferzeit 1-3 Werktage

Kurzinformation
Sprache:
Englisch
ISBN:
9783540608141
Seitenzahl:
168
Auflage:
-
Erschienen:
1996-01-01
Mit diesem Kauf sparst Du 2,06 kg CO2

Mehr Informationen zum Zustand
Green Tree

Gebrauchte Bücher kaufen

Information
Das Buch befindet sich in einem sehr guten, unbenutzten Zustand.
Information
Das Buch befindet sich in einem sehr guten, gelesenen Zustand. Die Seiten und der Einband sind intakt. Buchrücken/Ecken/Kanten können leichte Gebrauchsspuren aufweisen.
  • Sauberer Zustand, Seiten und Bindung etwas abgenutzt
  • Knicke oder Markierungen nicht mehr als 5%
  • CDs und Zugangscodes verwendbar
Information
Das Buch befindet sich in einem guten, gelesenen Zustand. Die Seiten und der Einband sind intakt. Buchrücken/Ecken/Kanten können Knicke/Gebrauchsspuren aufweisen.
Information
Das Buch befindet sich in einem lesbaren Zustand. Die Seiten und der Einband sind intakt, jedoch weisen Buchrücken/Ecken/Kanten starke Knicke/Gebrauchsspuren auf. Zusatzmaterialien können fehlen.

Neues Buch oder eBook (pdf) kaufen

Information
Neuware - verlagsfrische aktuelle Buchausgabe.
Natural Handgeprüfte Gebrauchtware
Coins Schnelle Lieferung
Check Faire Preise
Du sparst 52,84 € (49%)

inkl. MwSt. Versandinformationen

Lieferzeit 1-3 Werktage

54,16 €

Lieferzeit 1-3 Werktage

Weitere Zahlungsmöglichkeiten  
Zahlungsarten

Beschreibung

Interest Rate Dynamics, Derivatives Pricing, and Risk Management (Lecture Notes in Economics and Mathematical Systems, 435, Band 435)

There are two types of tenn structure models in the literature: the equilibrium models and the no-arbitrage models. And there are, correspondingly, two types of interest rate derivatives pricing fonnulas based on each type of model of the tenn structure. The no-arbitrage models are characterized by the work of Ho and Lee (1986), Heath, Jarrow, and Morton (1992), Hull and White (1990 and 1993), and Black, Dennan and Toy (1990). Ho and Lee (1986) invent the no-arbitrage approach to the tenn structure modeling in the sense that the model tenn structure can fit the initial (observed) tenn structure of interest rates. There are a number of disadvantages with their model. First, the model describes the whole volatility structure by a sin gle parameter, implying a number of unrealistic features. Furthennore, the model does not incorporate mean reversion. Black-Dennan-Toy (1990) develop a model along tbe lines of Ho and Lee. They eliminate some of the problems of Ho and Lee (1986) but create a new one: for a certain specification of the volatility function, the short rate can be mean-fteeting rather than mean-reverting. Heath, Jarrow and Morton (1992) (HJM) construct a family of continuous models of the term struc ture consistent with the initial tenn structure data.

Produktdetails
Einband:
paperback
Seitenzahl:
168
Erschienen:
1996-01-01
Sprache:
Englisch
EAN:
9783540608141
ISBN:
9783540608141
Gewicht:
259 g
Auflage:
-
Alle gebrauchten Bücher werden von uns handgeprüft.
So garantieren wir Dir zu jeder Zeit Premiumqualität.

Über den Autor


Entdecke mehr vom Verlag


Gut
54,16 €
Entdecke mehr zum Thema