


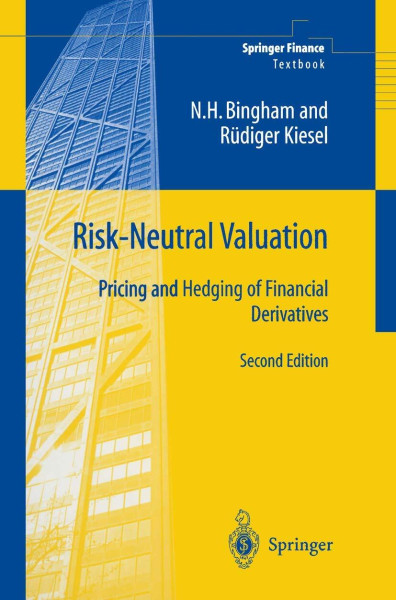
Risk-Neutral Valuation: Pricing and Hedging of Financial Derivatives (Springer Finance)
Kurzinformation

 Handgeprüfte Gebrauchtware
 Schnelle Lieferung
 Faire Preise
inkl. MwSt. Versandinformationen
Artikel zZt. nicht lieferbar
Artikel zZt. nicht lieferbar

Beschreibung
Since its introduction in the early 1980s, the risk-neutral valuation principle has proved to be an important tool in the pricing and hedging of financial derivatives. Following the success of the first edition of ‘Risk-Neutral Valuation’, the authors have thoroughly revised the entire book, taking into account recent developments in the field, and changes in their own thinking and teaching. In particular, the chapters on Incomplete Markets and Interest Rate Theory have been updated and extended, there is a new chapter on the important and growing area of Credit Risk and, in recognition of the increasing popularity of Lévy finance, there is considerable new material on: · Infinite divisibility and Lévy processes · Lévy-based models in incomplete markets Further material such as exercises, solutions to exercises and lecture slides are also available via the web to provide additional support for lecturers.
Produktdetails

So garantieren wir Dir zu jeder Zeit Premiumqualität.
Entdecke mehr vom Verlag


