LeafNachhaltiges Unternehmen CoinFaire Preise PackageSchneller und kostenloser Versand ab 14,90 € Bestellwert
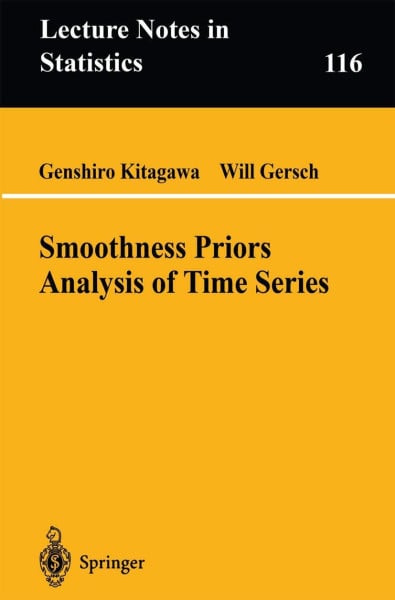
Smoothness Priors Analysis of Time Series (Lecture Notes in Statistics, 116, Band 116)

Smoothness Priors Analysis of Time Series (Lecture Notes in Statistics, 116, Band 116)

inkl. MwSt. Versandinformationen

Lieferzeit 1-3 Werktage

121,16 €

Lieferzeit 1-3 Werktage

Kurzinformation
Sprache:
Englisch
ISBN:
9780387948195
Verlag:
Seitenzahl:
290
Auflage:
-
Erschienen:
2013-10-04
Mit diesem Kauf sparst Du 2,06 kg CO2

Mehr Informationen zum Zustand
Green Tree

Gebrauchte Bücher kaufen

Information
Das Buch befindet sich in einem sehr guten, unbenutzten Zustand.
Information
Das Buch befindet sich in einem sehr guten, gelesenen Zustand. Die Seiten und der Einband sind intakt. Buchrücken/Ecken/Kanten können leichte Gebrauchsspuren aufweisen.
  • Sauberer Zustand, Seiten und Bindung etwas abgenutzt
  • Knicke oder Markierungen nicht mehr als 5%
  • CDs und Zugangscodes verwendbar
Information
Das Buch befindet sich in einem guten, gelesenen Zustand. Die Seiten und der Einband sind intakt. Buchrücken/Ecken/Kanten können Knicke/Gebrauchsspuren aufweisen.
Information
Das Buch befindet sich in einem lesbaren Zustand. Die Seiten und der Einband sind intakt, jedoch weisen Buchrücken/Ecken/Kanten starke Knicke/Gebrauchsspuren auf. Zusatzmaterialien können fehlen.

Neues Buch oder eBook (pdf) kaufen

Information
Neuware - verlagsfrische aktuelle Buchausgabe.
Natural Handgeprüfte Gebrauchtware
Coins Schnelle Lieferung
Check Faire Preise

inkl. MwSt. Versandinformationen

Lieferzeit 1-3 Werktage

121,16 €

Lieferzeit 1-3 Werktage

Weitere Zahlungsmöglichkeiten  
Zahlungsarten

Beschreibung

Smoothness Priors Analysis of Time Series (Lecture Notes in Statistics, 116, Band 116)

Smoothness Priors Analysis of Time Series addresses some of the problems of modeling stationary and nonstationary time series primarily from a Bayesian stochastic regression "smoothness priors" state space point of view. Prior distributions on model coefficients are parametrized by hyperparameters. Maximizing the likelihood of a small number of hyperparameters permits the robust modeling of a time series with relatively complex structure and a very large number of implicitly inferred parameters. The critical statistical ideas in smoothness priors are the likelihood of the Bayesian model and the use of likelihood as a measure of the goodness of fit of the model. The emphasis is on a general state space approach in which the recursive conditional distributions for prediction, filtering, and smoothing are realized using a variety of nonstandard methods including numerical integration, a Gaussian mixture distribution-two filter smoothing formula, and a Monte Carlo "particle-path tracing" method in which the distributions are approximated by many realizations. The methods are applicable for modeling time series with complex structures.

Produktdetails

Einband:
paperback
Seitenzahl:
290
Erschienen:
2013-10-04
Sprache:
Englisch
EAN:
9780387948195
ISBN:
9780387948195
Verlag:
Gewicht:
348 g
Auflage:
-
Alle gebrauchten Bücher werden von uns handgeprüft.
So garantieren wir Dir zu jeder Zeit Premiumqualität.

Über den Autor


Entdecke mehr vom Verlag


Gut
121,16 €
Entdecke mehr zum Thema