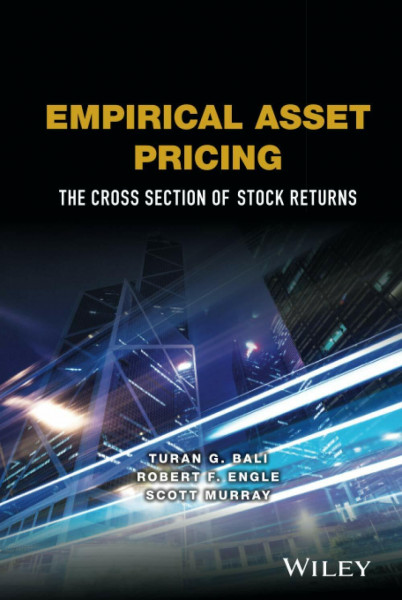
Empirical Asset Pricing: The Cross Section of Stock Returns
Kurzinformation
 Handgeprüfte Gebrauchtware
 Schnelle Lieferung
 Faire Preise
inkl. MwSt. Versandinformationen
Lieferzeit 1-3 Werktage
Lieferzeit 1-3 Werktage

Beschreibung
“Bali, Engle, and Murray have produced a highly accessible introduction to the techniques and evidence of modern empirical asset pricing. This book should be read and absorbed by every serious student of the field, academic and professional.” Eugene Fama, Robert R. McCormick Distinguished Service Professor of Finance, University of Chicago and 2013 Nobel Laureate in Economic Sciences “The empirical analysis of the cross-section of stock returns is a monumental achievement of half a century of finance research. Both the established facts and the methods used to discover them have subtle complexities that can mislead casual observers and novice researchers. Bali, Engle, and Murray’s clear and careful guide to these issues provides a firm foundation for future discoveries.” John Campbell, Morton L. and Carole S. Olshan Professor of Economics, Harvard University “Bali, Engle, and Murray provide clear and accessible descriptions of many of the most important empirical techniques and results in asset pricing.” Kenneth R. French, Roth Family Distinguished Professor of Finance, Tuck School of Business, Dartmouth College “This exciting new book presents a thorough review of what we know about the cross-section of stock returns. Given its comprehensive nature, systematic approach, and easy-to-understand language, the book is a valuable resource for any introductory PhD class in empirical asset pricing.” Lubos Pastor, Charles P. McQuaid Professor of Finance, University of Chicago Empirical Asset Pricing: The Cross Section of Stock Returns is a comprehensive overview of the most important findings of empirical asset pricing research. The book begins with thorough expositions of the most prevalent econometric techniques with in-depth discussions of the implementation and interpretation of results illustrated through detailed examples. The second half of the book applies these techniques to demonstrate the most salient patterns observed in stock returns. The phenomena documented form the basis for a range of investment strategies as well as the foundations of contemporary empirical asset pricing research. Empirical Asset Pricing: The Cross Section of Stock Returns also includes: Discussions on the driving forces behind the patterns observed in the stock market An extensive set of results that serve as a reference for practitioners and academics alike Numerous references to both contemporary and foundational research articles Empirical Asset Pricing: The Cross Section of Stock Returns is an ideal textbook for graduate-level courses in asset pricing and portfolio management. The book is also an indispensable reference for researchers and practitioners in finance and economics. Turan G. Bali, PhD, is the Robert Parker Chair Professor of Finance in the McDonough School of Business at Georgetown University. The recipient of the 2014 Jack Treynor prize, he is the coauthor of Mathematical Methods for Finance: Tools for Asset and Risk Management, also published by Wiley. Robert F. Engle, PhD, is the Michael Armellino Professor of Finance in the Stern School of Business at New York University. He is the 2003 Nobel Laureate in Economic Sciences, Director of the New York University Stern Volatility Institute, and co-founding President of the Society for Financial Econometrics. Scott Murray, PhD, is an Assistant Professor in the Department of Finance in the J. Mack Robinson College of Business at Georgia State University. He is the recipient of the 2014 Jack Treynor prize.
Produktdetails
So garantieren wir Dir zu jeder Zeit Premiumqualität.