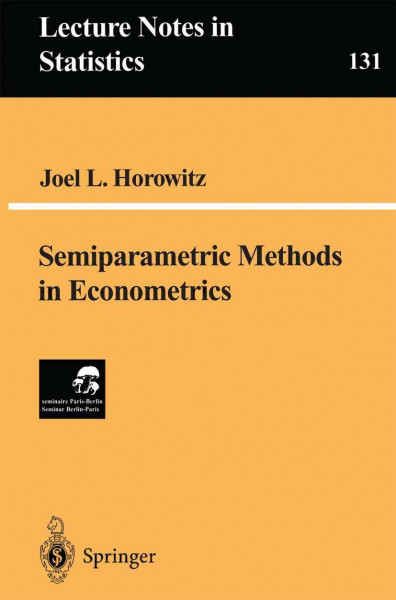
Semiparametric Methods in Econometrics (Lecture Notes in Statistics, 131, Band 131)
inkl. MwSt. Versandinformationen
Lieferzeit 1-3 Werktage
Lieferzeit 1-3 Werktage
Kurzinformation
 Handgeprüfte Gebrauchtware
 Schnelle Lieferung
 Faire Preise
inkl. MwSt. Versandinformationen
Lieferzeit 1-3 Werktage
Lieferzeit 1-3 Werktage

Beschreibung
Many econometric models contain unknown functions as well as finite- dimensional parameters. Examples of such unknown functions are the distribution function of an unobserved random variable or a transformation of an observed variable. Econometric methods for estimating population parameters in the presence of unknown functions are called "semiparametric." During the past 15 years, much research has been carried out on semiparametric econometric models that are relevant to empirical economics. This book synthesizes the results that have been achieved for five important classes of models. The book is aimed at graduate students in econometrics and statistics as well as professionals who are not experts in semiparametic methods. The usefulness of the methods will be illustrated with applications that use real data.
Produktdetails
So garantieren wir Dir zu jeder Zeit Premiumqualität.
Entdecke mehr vom Verlag